
- 01Tungsten tops US$3,000/mtu on curbs and defence demand.
- 02Sky’s Tallebung: A$438m NPV, 69% IRR; 2028 production target.
- 03Drilling lifts tungsten prospects.
If you weren’t glued to Sunday night’s grand final, I feel for you. It was the best decider in a long time. Two NSW clubs, two shades of blue, and the Roosters got there by a single point over a Knights side that simply refused to go away.
Both were deserving winners. Twelve months ago Newcastle were holding the wooden spoon. If you’d told a Knights fan last September they’d take the Roosters to the final whistle in a grand final, they’d have asked what you were drinking.
I know the feeling. Tell a fund manager in 2023 that tungsten would be the best-performing commodity on the board and you’d have got the same look.
APT sat around US$300/mtu for the best part of a decade. Then China, which supplies roughly 80% of the world, tightened export licences in February 2025, NATO started restocking, and the drone age discovered you can’t build loitering munitions out of goodwill. Industry pricing now has APT north of US$3,000/mtu. Wooden spoon to grand final, in metal form.
Tungsten’s whole personality is toughness. Highest melting point of any metal, nearly as hard as diamond, and sitting in the tip of every armour-piercing round and cutting tool that matters.
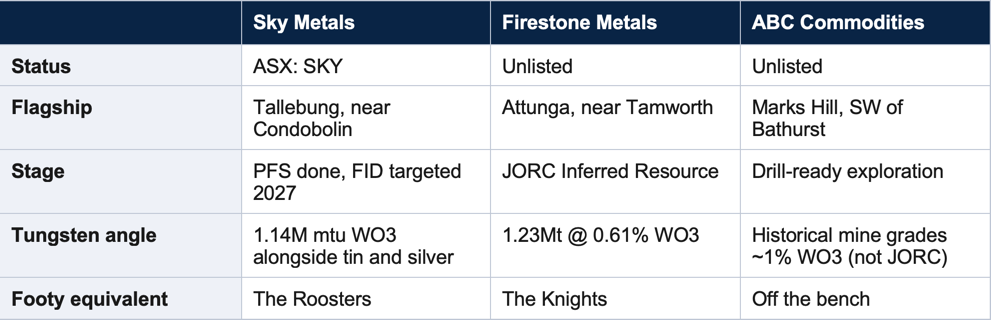
So it’s fitting that some of the more interesting new tungsten stories are coming out of NSW, a state with plenty of practice at being stubborn. Here are three I’m watching: one listed, two unlisted.
The Roosters: Sky Metals
Sky Metals (ASX: SKY) is the Roosters here: the experienced, well-drilled side that knows how to close out a big game.
Tallebung, about 70km north-west of Condobolin, started life as a tin story that tungsten quietly gatecrashed. The July upgrade took the resource to 32.7Mt for 36,800t of tin, 1.14 million mtu of WO3 and a maiden 9.94Moz of silver.
The PFS that followed outlined a 3Mtpa open pit with A$139m capex, a 69% IRR, an NPV of A$438m and payback inside 17 months. FID is pencilled in for 2027, first production for mid-2028.
What has my attention is tungsten moving up the order. Diamond holes have shown coarse wolframite, and rock chips at Theirman Mines, about 20km away, came back as high as 7.44% WO3.
When I sat down with MD Oliver Davies last week, he was clear that tungsten is becoming a bigger part of the Tallebung story, not a footnote.
Listen: Sky Metals: shallow tin hits and high-grade tungsten
Watch: Sky Metals PFS lands: tin, silver, and tungsten drive the Tallebung story
Read: Sky maps rapid payback at Tallebung | High-grade tungsten at Theirman Mines
The Knights: Firestone Metals (unlisted)
Firestone is the Knights: hungry, gritty, and punching well above where anyone had them a year ago.
Its flagship Attunga project sits 20km north of Tamworth on mostly freehold land, with power, rail and water close by. Attunga carries a JORC 2012 Inferred Resource of 1.23Mt at 0.61% WO3 for about 7.5kt contained WO3, which the company pitches as the highest-grade tungsten resource in NSW.
It’s not big, but grade is king when the product sells for what tungsten does now, and a gravity flowsheet keeps the capex conversation short. Gravity work also points to an untested extension that could stretch the strike from about 100m to 500m.
The team is the bit I like. Paul Newling has spent 35 years designing and commissioning tungsten plants, and Martin McQuade is the former CEO of Tungsten Mining Group. In a junior, people who have actually built the thing before are worth more than any 3D block model.
There’s also the Minter licence in the Wagga Tin-Tungsten Belt, between Tallebung and Ardlethan, so Sky and Firestone could end up neighbours.
CEO Ryan Mount joined us back in May if you want to hear it from him directly.
Off the Bench: ABC Commodities (unlisted)
Every grand final side needs someone off the bench who changes the game. ABC is an unlisted explorer with three NSW projects, and the one I care about is Marks Hill, 90km south-west of Bathurst. It’s a 15km trend with four wolframite occurrences, including the old Marks Hill mine, where historical production grades were estimated at around 1% WO3.
The first target is Reid’s Flat, an outcropping greisen roughly 180m by 40m where surface sampling has averaged 0.5% WO3, with a ten-hole RC program planned to test it at depth.
This is pure exploration. None of the numbers are JORC, so treat it as a discovery bet, not a resource story. But if that greisen holds at depth, it gets interesting quickly.
Crystal Ridge on the Mid North Coast and Woodlawn East, next door to Develop’s Woodlawn mine, add copper, tin, gold and zinc on the side.
Full-Time Score
Tungsten isn’t a fad. China’s grip isn’t loosening, Western governments are writing cheques, and new supply takes years to build. The producers have already been re-rated.
If there’s a next leg, it’s more likely to be in the projects still proving themselves, which is exactly where the risk lives too.
Sunday reminded me that the gap between the favourite and the battler can be one point, and that both can deserve to win. Investing in this space feels much the same.
My takeaways are less romantic than the footy: back grade, back people who have built plants before, and know which stage of the game you’re buying into.
For the bigger picture, start with The Weekly Finger: Resource Wars and the Tungsten Trap and Has tungsten been an oversight for investors?.
And if you’re a sophisticated investor and want to talk about what we’re seeing in the space, drop me a line.
General information only. This article does not take into account your objectives, financial situation or needs and is not an offer of securities. Firestone Metals and ABC Commodities are unlisted companies. Some exploration results referred to are historical and not reported under the JORC Code. SmallCaps may have a commercial relationship with companies mentioned.
Get the wire before the market opens.
The ASX small-cap stories that matter, filed before 9am AEST. Curated by the Small Caps desk.