

- 01MSCI mining ~2.2%; could rise to ~5%.
- 02Cycle clock: early boom; AI/data demand.
- 03Firefly Green Bay: 42% IRR, 32y life.
- 04Sunstone Ecuador porphyry copper-gold assets.
G'day team,
Just got back from two full days on the mic at Resources Rising Stars on the Gold Coast last week, and my voice has more or less given up on me.
Massive event again this year, run beautifully by Nicholas Read and the Read Corporate team.
Rather than the usual format this week, I've pulled together the key takeaway from every conversation, grouped by theme, with the full interview linked underneath if you want to hear it straight from the source.
The Big Picture
Charlie Aitken, Recall Investment opened the conference and set the tone for the whole two days.
His numbers are extraordinary: metals and mining make up just 2.2% of the MSCI World Equity Index, which he reckons is a straightforward misrepresentation of how critical these businesses are to the global economy. He thinks that weighting could double to five percent inside four or five years, meaning pretty much every large cap miner in the world could be undervalued by a hundred percent.
And if you want proof that mining conferences matter, his story about Twiggy Forrest ringing him literally every day for a month begging him to visit Fortescue two decades ago is worth the watch on its own.
https://www.youtube.com/shorts/DSOO9FelVH8
Lion Selection Group (ASX: LSX) Hedley Widdup took Charlie's thesis and put a clock on it. Lion's cycle clock puts the sector somewhere past six o'clock, meaning we're through the bust and into the early boom, though Hedley wouldn't give me the exact hour on camera, fair enough given there was a $500 gift card riding on it at the RRS trivia.
His view is this cycle looks less like the 2016-21 mini boom and more like the noughties China boom, except the demand driver this time is data centre build out and AI compute rather than Chinese steel mills.
Same punchline as Charlie though, mining needs to go from a two percent weighting to something closer to five, and something else in the index has to give way for that to happen.
https://www.youtube.com/watch?v=9f1rfugz7Q4&t=57s
Copper
Firefly Metals (ASX: FFM), Darren Cooke had the number of the conference for me. Their PEA on Green Bay in Newfoundland came back with a 42% IRR and a 32 year mine life, using a conservative $5 a pound copper price when spot was sitting at $6.72 the day we spoke.
The upscaled case gets to 100,000 tonnes of copper equivalent a year and $6.5 billion of free cash flow after tax. Nine rigs are turning right now, six underground and three on surface, chasing more of the high grade VMS system that keeps growing every time they drill it.
https://www.youtube.com/watch?v=liRUcj_uVnI
Sunstone Metals (ASX: STM), Patrick Duffy. Sunstone**** is sitting on two large porphyry gold-copper systems in Ecuador, Bramaderos and El Palmar, five million ounces combined, with a resource upgrade at Bramaderos due next month.
The read-through I liked was the DGR Global connection, Nick Mather's mob, the same team behind SolGold's Cascabel discovery which was acquired this year for $1.7 billion.
Patrick reckons Sunstone trades at around $9 an ounce against peers sitting at $30 to $50, and DGR believes El Palmar could be a genuine repeat of Cascabel.
https://www.youtube.com/watch?v=xzWh5bvp9TM
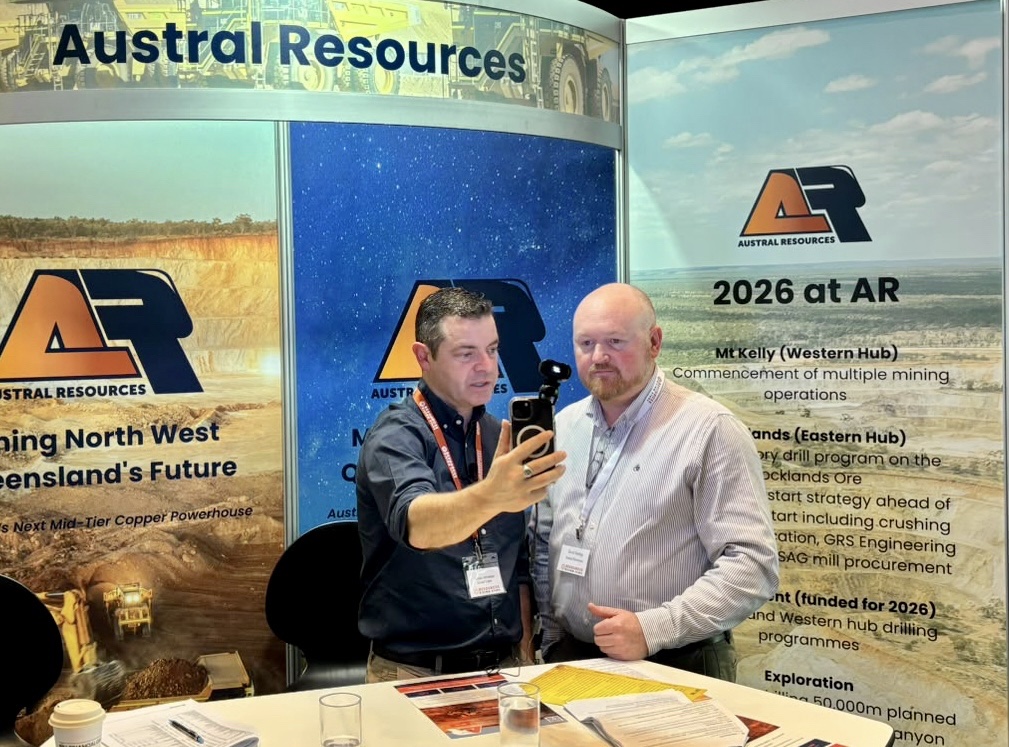
Austral Resources (ASX: AR1), David Newling. AR1 is the only company in the country able to process both oxide and sulphide copper ore, which gives other junior asset owners a production pathway as well as feeding their own.
First shipping containers for the SAG mill at Rocklands have landed, restart's still on track for Q3 2027.
https://www.youtube.com/shorts/K0Q_bt3m_rU
Kaoko Metals (ASX: KAO), Gerard O'Donovan. Kaoko has been the standout share price mover of the whole conference. Their Namibian copper project has thrown up back to back visible copper intercepts, 50 metres and 60 metres of it, and they've just banked $20 million to bring in a second rig. Silver's showing up as an accessory mineral too, assays due in a few weeks.
Gold
Astral Resources (ASX: AAR), Marc Ducler. Astral has 1.75 million ounces at the Mandilla hub near Kalgoorlie alone, 2.1 million ounces across the group, and has just doubled the vertical extent of mineralisation at Thea Deeps below the current resource shell. DFS still on track for the March quarter of 2027.
https://www.youtube.com/shorts/k_8sEYMUQkg
Great Boulder Resources (ASX: GBR), Andrew Paterson. GBR has two assets worth watching near Meekatharra: Sidewell, which sits inside a historic multi-million ounce field and keeps growing at Mulga Bill (still open north, east and at depth after some 200,000 metres of drilling), and Peak Hill, picked up off West Gold, who stayed on as a 20% cornerstone holder.
They drilled 27,000 metres in the first seven weeks at Peak Hill, more than their old full year budget, chasing an exploration target of a million ounces.
https://www.youtube.com/watch?v=js3s9DLDR3c&pp=0gcJCf4LAYcqIYzv
Saturn Metals (ASX: STN), Ian Bamborough. Saturn is building a definitive feasibility study for a 2.8 million ounce open pit heap leach gold operation at Apollo Hill in the Eastern Goldfields, due out this December.
The resource is tracking toward 3 million ounces and Ian reckons it could ultimately get to 5 million, helped by a genuinely low 1.5:1 waste to ore strip ratio.
https://www.youtube.com/watch?v=6n1EmEQhLCA
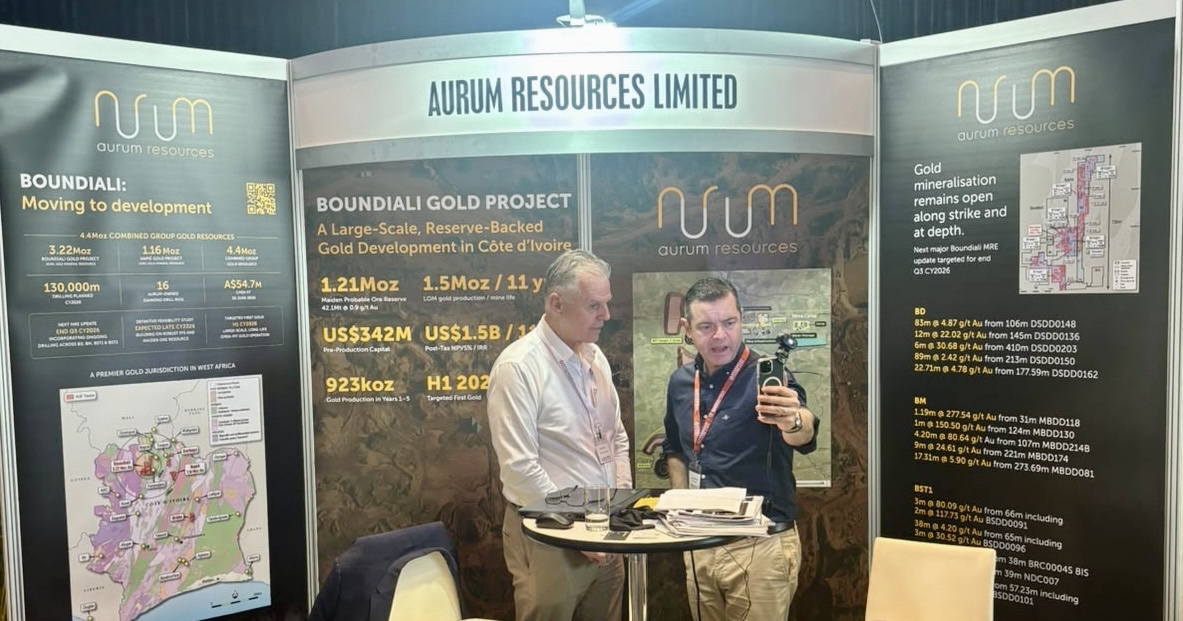
Aurum Resources (ASX: AUE), Mark Strizek. Aurum is advancing the Bundiali and Napie gold projects in Cote d'Ivoire, 3.22 million ounces at Bundiali and 1.16 million at Napie, and both numbers still growing.
A PFS landed in June, DFS due by year end, and another resource update adding 60,000 metres of drilling is coming that should lift both the indicated category and the headline ounces.
Mark's team built and sold their last Cote d'Ivoire project for around $740 million, so this is very much the rinse and repeat story, first Bundiali into production, Napie potentially following within five years, pushing Aurum toward mid tier producer status.
https://youtube.com/shorts/OrtHv6nLdfk?si=ao_fCv6dnxqxb4mg
Great Southern Mining (ASX: GSN), Matthew Keane. GSN has gold moving on two fronts, Golden Boulder and Amy Clark in WA (3.5 and 4.7 kilometres of strike respectively, both still shallow), and Edinburgh Park near Collinsville in Queensland, where Goldfields is funding exploration as a joint venture partner.
Between 70 and 80 drill holes are sitting in the lab or just starting to report, so expect a heavy run of news over coming weeks.
https://www.youtube.com/shorts/g79UrpexE2E
Javelin Minerals (ASX: JAV), Brett Mitchell. Javelin just landed final mining approval at the Eureka gold project near Kalgoorlie and is shovel ready for production, finalising a toll milling agreement with nearby operators.
They're also drilling deep diamond holes, down to a kilometre, into untested copper-gold porphyry targets at KUJI.
https://youtube.com/shorts/k0fxzdXu6RE?si=PgiwrnLLwcVkPhkl
Torque Metals (ASX: TOR), Craig Jones. TOR has renamed the old Paris project the "Ritz", and for good reason, with a recent hit of 11 metres at 459 grams a tonne showing just how well endowed that ground is.
Resource across the group grew 67% to 351,000 ounces, and the team, the same one that built Spartan Resources, is targeting a million ounces inside two years under what they're calling Project RPM.
https://www.youtube.com/shorts/VAM5vcJ3lCc
Critical Minerals, Uranium and the Odd One Out
Basin Energy (ASX: BSN), Pete Moorhouse. Basin sold down their deep Athabasca uranium project in Canada to focus on rare earths in North Queensland, where first drilling has already returned good grades of neodymium and praseodymium plus some terbium, with no caesium contamination.
There's a nice second leg too: a Swedish uranium policy reversal from January this year has turned an old, previously unmineable discovery into a genuine uranium option in a jurisdiction nobody else is looking at.
https://www.youtube.com/watch?v=I2eP4Df9uvU&t=10s
Greenvale Energy (ASX: GRV), Alex Cheeseman. Greenvale is hunting a uranium elephant at the Thunderball project in the Northern Territory. An airborne survey has thrown up 13 targets, two historic prospects confirmed and one brand new one, the Powers Prospect, ready to drill.
The NT's fast tracked critical minerals permitting is a genuine edge here, Alex reckons it's the fastest path to getting tonnes out of the ground of anywhere in the country.
https://youtube.com/shorts/UD6JCU4BRk4?si=225qCHxZbGB9VCxk
Killi Resources (ASX: KLI), Hamish Halliday. Killi has pivoted a private magnetite holding of over a decade into a public company at exactly the right time, feeding the shift to electric arc furnace green steel. Their magnetite at Lodestone in WA's Midwest is 10 to 100 times coarser than anything else in the Yilgarn, meaning simple crush and screen processing straight to a 69% product.
Current resource covers only 20% of the known system, and they're aiming to quadruple it to half a billion tonnes over the next 12 to 18 months.
https://www.youtube.com/watch?v=gdLRRj89hWg&pp=0gcJCf4LAYcqIYzv
Advanced Engineered Materials (ASX: AEM), Richard Seville. AEM makes high purity alumina out of Quebec, feeding advanced ceramics, sapphire and the fast growing semiconductor space.
They just signed an exclusive supply deal with a high end Swiss ceramics manufacturer, and the pitch is straightforward: made outside China, for customers who need to be able to say the same thing.
https://www.youtube.com/watch?v=s8OFxDCPLCw
PMET Resources (ASX: PMT, TSX: PMET), Ken Brinsden. PMET owns Shaakichiuwaanaan in Quebec's James Bay region, try saying that three times fast, the largest lithium pegmatite resource in the Americas and a top ten global ranking on its own.
An updated feasibility study lands in the next couple of months, refreshing the prior study ahead of an expected final investment decision in the latter part of next year. The real kicker though is the byproduct credit: it's the world's largest hard rock caesium resource, and they haven't even finished drilling it, plus strong tantalum credits, both of which push the cost of producing the lithium right down.
Ken's also seeing real momentum out of North America specifically, sovereign supply chain politics doing a lot of the heavy lifting there.
https://youtube.com/shorts/p0voBKKYdI8?si=wuB46KIej6g8ZcXc
Lake Resources (ASX: LKE), Stu Crowe. Lake is in the final stages of EIA permitting for Kachi in Argentina's Catamarca province, community consultation wrapped up the Monday before we spoke and it's now sitting with the mines department and the provincial government, with Stu hopeful the permit lands within a week or so.
He's bullish on the lithium price rebound holding, demand keeps growing and there's no incentive price yet to bring new supply on. Once the permit's through, Lake moves straight into financing and offtake, and there's already a data room full of parties looking at both.
Worth noting the recent trend across the industry: offtake deals increasingly come with prepayments and floor prices attached, which makes the financing side a lot easier to lock down.
https://youtube.com/shorts/180dIhxLVTE?si=GU2cZZFyF2Zumjy1
Minerals Exploration (ASX: MEX), Jason Beckton. MEX is chasing brownfields epithermal gold silver right next to Oceana Gold's Waihi mine in New Zealand, with visible gold already found and 3D modelling underway.
The side story worth watching is tungsten at their Invincible project on the South Island, grades up to 6% recently, likely averaging one and a half to two percent across a tabular system once it's drilled out properly.
https://www.youtube.com/shorts/hRZNZf9bJjY
Flynn Gold (ASX: FG1), Neil Marston. Flynn is all in on Tasmania now, drilling a resource extension at Golden Ridge (targeting 450,000 to 520,000 ounces) alongside a genuinely interesting tungsten story at Fire Tower, where a recent hole returned 17 metres at 2.3 grams gold and 0.51% WO3.
For context, Group 6 Metals just relisted with a $900 million market cap on a reserve grade of 0.9% WO3, so half a percent at Fire Tower is a very solid outcome.
https://www.youtube.com/watch?v=kdhMM_JB7Wc
Closing Colour
Kerry Stevenson from Gold Events was working the floor the whole conference, with a quick stop to grill Andrew Paterson from Great Boulder the second he came off stage, always a good sign when that happens.
Her main message was blunt and I happen to agree with it: currency debasement is the real driver of the gold price, not gold "going up", and if you're not comfortable owning physical metal, the miners give you the leverage instead.
Her own gold event runs 13 to 15 October at the Crown in Barangaroo, Rick Rule's speaking, get your ticket at https://goldconference.com.au/agc-26
https://www.youtube.com/watch?v=E_k64i7Mj9s
To close it out, Nicholas Read's read on the room summed up the whole two days better than I could.
Tungsten went from a page five afterthought to a page three headline this year, largely thanks to global conflict driving demand, there's apparently fifteen kilograms of silver in every cruise missile too, which puts a few of this week's tungsten and silver stories in a different light.
And the crowd told its own story, he's got investors who fly in from Monaco and London every single year just for this conference. If the room really is where the next decade's winners get found, as both Charlie and Hedley reckon, it's hard to argue anyone does a better job of filling that room than Read Corporate.
Stay safe and all the best,
James
Get the wire before the market opens.
The ASX small-cap stories that matter, filed before 9am AEST. Curated by the Small Caps desk.